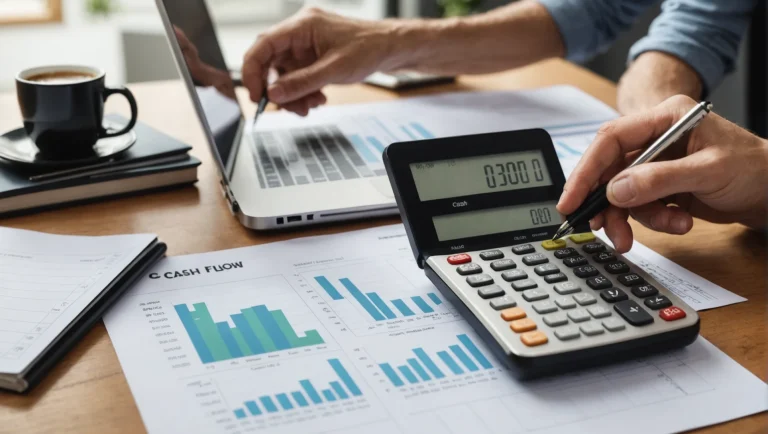

The cash flow metrics for small businesses worth tracking are operating cash flow, free cash flow, the cash conversion cycle, days sales outstanding, days payable outstanding, the operating cash flow ratio and debt service coverage. Seven numbers, all derived from data you already have, and together they tell you whether you can pay what you owe over the next few months.
They matter because profit and cash are different things, and only one of them pays wages. A business can book a record month, show a healthy margin, and still be unable to cover payroll, because the revenue is sitting in unpaid invoices while the costs have already cleared the account. Cash flow metrics are how you see that coming while there is still time to act.
The Bottom Line
- Operating cash flow is the first number to learn: net income plus non-cash expenses plus the change in working capital.
- The cash conversion cycle explains why growth feels like poverty. Growing businesses buy before they get paid, and the gap widens before it closes.
- Days sales outstanding is the most immediately useful of the seven, because chasing invoices is something you can do this afternoon.
- Review cash weekly. It is the one metric where monthly is too slow, because cash problems compound.
- A positive net profit with negative operating cash flow is the classic warning sign, and it almost always means receivables or stock.
Save 80% of delivery management time
We handle everything:
- Dedicated operations manager
- Real-time tracking dashboard
- Automated customer notifications
- Urgent issue resolution
Why cash flow metrics differ from profit metrics
Accounting records a sale when you make it. Your bank records it when the money lands. In a business that invoices on terms, those two events can be sixty days apart, and every cash problem a small business has lives in that gap.
This is why profit margin and cash flow have to be tracked separately rather than treated as versions of the same thing. Margin tells you whether the work is worth doing. Cash flow tells you whether you can survive doing it. A business with excellent margins and terrible collection habits will fail, and the margin report will look fine the whole way down.
The practical consequence is a different review rhythm. Margin is a monthly number because it needs a full month of costs to mean anything. Cash is a weekly number because a gap you spot on Monday can often be closed by Friday, and one you spot in six weeks cannot.
Operating cash flow
Operating cash flow is the cash your normal trading activity actually generates, stripped of financing and one-off asset sales.
Operating cash flow = net income + non-cash expenses + change in working capital
Non-cash expenses are mostly depreciation and amortisation: real costs for accounting, but no money left the building this month. The change in working capital is where the interesting part hides, because it captures money tied up in stock and in invoices waiting to be paid. Getting the expense side classified consistently makes this far easier to read month to month, and the business expense categories worth tracking is a practical starting structure.
What to look for: operating cash flow should be positive and should broadly track net income over a few months. When net income is positive and operating cash flow is negative, you are making money on paper and losing it in practice, and the culprit is nearly always one of two things. Either receivables are growing because customers are paying slower, or stock is growing because you are buying faster than you sell.
Free cash flow
Free cash flow is what remains after you have paid for the equipment and vehicles needed to keep operating.
Free cash flow = operating cash flow − capital expenditure
This is the number that tells you what is available for paying down debt, taking distributions or funding growth from your own resources. A business with strong operating cash flow and no free cash flow is spending everything it generates on keeping the machine running, which is viable but leaves no cushion.
Free cash flow is also the honest input to a purchase decision. When you are weighing a second vehicle or a new chiller, the question is what it does to free cash flow and how fast it pays back, which is the same arithmetic as calculating ROI on the purchase. Cash flow tells you whether you can afford it; ROI tells you whether it is worth affording.
The cash conversion cycle
The cash conversion cycle counts the days between money going out and money coming back in.
Cash conversion cycle = days inventory outstanding + days sales outstanding − days payable outstanding
Read it as a story. You buy stock and it sits for a while (days inventory outstanding). You sell it and wait to be paid (days sales outstanding). Meanwhile you have delayed paying your own supplier (days payable outstanding), which funds part of the gap. What is left is the number of days you are financing out of your own pocket.
A forty-day cycle means every pound of sales ties up cash for forty days before returning. Double your sales and you double the amount tied up, which is precisely why fast growth creates cash crises in otherwise healthy businesses. The growth is real, the profit is real, and the bank balance still falls.
Three levers shorten it: sell stock faster, collect faster, or pay later. The third is the easiest to overuse, because stretching suppliers works right up until it damages a relationship you need.
Days sales outstanding
Days sales outstanding is the average number of days customers take to pay you.
DSO = (accounts receivable ÷ total credit sales) × number of days in the period
Of the seven metrics here, this is the one with the shortest path from measurement to action. A DSO of fifty-two days against thirty-day terms means your stated terms are decorative, and the fix is a process rather than a strategy: invoice on the day of delivery rather than at month end, state the due date rather than the terms, and chase at day thirty-one instead of day sixty.
Track it alongside an ageing list, not just as an average. One very large unpaid invoice can hold the average up while everything else is fine, and the average will not tell you which situation you are in.
If DSO is structurally high because of how your sector pays, that is a financing question rather than a collections one, and worth treating as such before it becomes urgent. Invoice financing exists for exactly that situation, releasing cash against invoices you have issued but not yet been paid for.
Days payable outstanding
Days payable outstanding is the mirror image: how long you take to pay suppliers.
DPO = (accounts payable ÷ cost of goods sold) × number of days in the period
Higher is better for your cash position and worse for your supplier relationships, which makes this the one metric on the list where the optimum is not the extreme. Supplier goodwill is worth real money when you need an urgent order filled or a payment deferred, and it is spent quickly by habitual late payment.
The sensible approach is to use the terms you have agreed rather than the terms you can get away with. Paying a thirty-day invoice on day twenty-nine is good cash management; paying it on day fifty is borrowing from someone who did not agree to lend.
The operating cash flow ratio
Operating cash flow ratio = operating cash flow ÷ current liabilities
This asks a direct question: does the cash your business generates cover what it owes in the near term? Above 1.0 means yes, with the cash from operations alone. Below 1.0 means the shortfall has to come from somewhere else, whether reserves, a facility or an owner’s loan.
It is a useful single-glance health check, and a better one than the current ratio for a small business, because it uses actual cash generated rather than assets that may or may not convert quickly. Stock counted as a current asset is only as liquid as your ability to sell it.
Debt service coverage ratio
DSCR = operating cash flow ÷ total debt service
Total debt service means the principal and interest falling due over the period. Lenders use this ratio to decide whether to lend to you, which is reason enough to know it before you apply, and typically want to see comfortably above 1.0 so there is headroom if trading dips. Work out your own figure before you start comparing what small business loan providers will offer, because the ratio largely determines which terms are realistically available to you.
It is worth tracking even with no debt, because it answers a question you will eventually face: how much borrowing could this business actually service? Running the number before you need to borrow is considerably more comfortable than running it during an application.
How the seven cash flow metrics fit together
| Metric | Formula | Review | What a bad reading means |
|---|---|---|---|
| Operating cash flow | Net income + non-cash expenses + Δ working capital | Weekly | Trading is consuming cash, not generating it |
| Free cash flow | Operating cash flow − capital expenditure | Monthly | Nothing left after keeping the lights on |
| Cash conversion cycle | DIO + DSO − DPO | Monthly | Growth will strain cash before it helps |
| Days sales outstanding | (Receivables ÷ credit sales) × days | Weekly | Customers pay later than your terms say |
| Days payable outstanding | (Payables ÷ COGS) × days | Monthly | Either straining suppliers or paying too early |
| Operating cash flow ratio | Operating cash flow ÷ current liabilities | Monthly | Near-term obligations exceed cash generated |
| Debt service coverage | Operating cash flow ÷ debt service | Quarterly | Limited headroom on existing or new borrowing |
The reporting layer that makes this manageable is a thirteen-week rolling forecast: known inflows and outflows week by week, updated every Monday. Thirteen weeks is far enough ahead to act and near enough to be reasonably accurate, and the act of updating it weekly is what surfaces problems early.
What these metrics do not tell you
Cash flow metrics are diagnostic, not strategic. They will tell you precisely when a squeeze is coming and say nothing about why the business is structured to produce one.
For the why, you need the adjacent numbers. Revenue growth metrics tell you whether the cash strain is the price of real growth or the symptom of a business running harder to stand still. Average order value often matters more than it looks here, because a higher value per order spreads fixed handling and delivery costs over more revenue and shortens the conversion cycle without changing anything about how you collect. And net promoter score is the early warning on the revenue side, since customers stop recommending you well before they stop ordering.
Cash flow sits inside the wider picture of which small business metrics to track and how often, and it is the group to get working first.
Frequently asked questions
What is the most important cash flow metric for a small business?
Operating cash flow. It is the one number that says whether normal trading produces usable cash, and every other metric here is either a component of it or a consequence.
How often should a small business review cash flow?
Weekly. Cash problems compound and become harder to reverse the longer they run, so the review interval needs to be short enough that you can still act. Thirty minutes every Monday against a rolling thirteen-week forecast is enough for most businesses.
Can a profitable business run out of cash?
Routinely. Profit is recorded when a sale is made; cash arrives when the invoice is paid. If customers take sixty days and suppliers take thirty, a profitable business funds that gap itself, and the faster it grows the larger the gap becomes.
What is a good cash conversion cycle?
Shorter than yours is now, which is the only benchmark that transfers across sectors. A business holding no stock and taking card payments can run a negative cycle; a wholesaler holding six weeks of inventory on sixty-day terms cannot. Track the direction rather than the absolute number.
What causes negative operating cash flow when profit is positive?
Almost always receivables or inventory. Either customers are paying more slowly than they were, so profit is accumulating as unpaid invoices, or stock is building faster than it sells. Both show up in the working capital component.
Where to start
Calculate operating cash flow for the last three months and put it beside net income for the same months. If the two lines move together, your cash cycle is working and you can move on to the margin questions. If they diverge, the gap is your diagnosis, and the next number to pull is days sales outstanding.
Local conditions shape all of this more than owners expect, since the pace customers pay at and the cost of covering a delivery area both vary by market. Our notes on running deliveries in Worcester, Massachusetts give a sense of how much that differs from one city to the next.
Then start the thirteen-week forecast. It is the single highest-return piece of financial admin a small business can take on, and it exists mainly to stop surprises, which is what cash problems almost always are.